
What the machine gaming duty increase actually says
Did the retail gambling sector dodge the bullet? Not quite. The UK machine gaming duty increase confirmed at the Budget is five percentage points, taking effect from April 2027. That is materially smaller than the roughly 40 per cent increase that circulated in pre-Budget briefing and was widely discussed across the trade press, and share prices moved accordingly on the day.
So the relief is genuine. The problem is that relief was measured against a worst case nobody wanted, not against the status quo. Five points is still five points, and where those points land matters more than how they compare to a rumour.
Here are the headline figures reported around the decision, with the party making each claim, because they are not all measuring the same thing.
| Figure | Source of the claim | What it covers |
|---|---|---|
| +5 percentage points, from April 2027 | Confirmed by the Chancellor at the Budget | The MGD change itself |
| Around 40 per cent increase | Widely discussed pre-Budget expectation | What operators had braced for |
| Up to 16,000 jobs; 1,500 betting shops and 34 casinos at risk | EY modelling cited by the Betting and Gaming Council, based on an MGD rise to 40 per cent | Sector-wide retail exposure |
| About £200m a year | Entain estimate | Annualised additional cost to its UK and Ireland online business |
| Up to £57m a year | British Horseracing Authority warning | Potential reduction in racing revenues |
Machine Gaming Duty, in plain terms
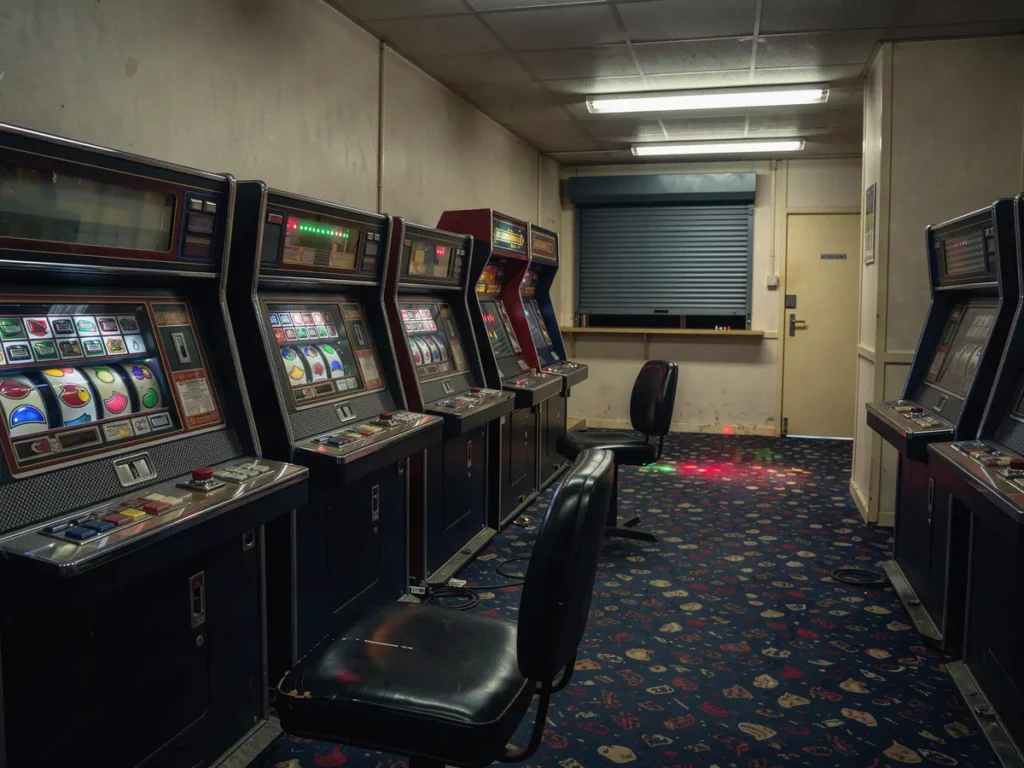
Machine Gaming Duty is a UK tax on the net takings of dutiable gaming machines, charged to the person who holds the machines on a premises rather than to the player. It applies across amusement arcades, pubs, bingo halls, bowling and leisure sites, betting shops and casinos, and is charged in bands, with the rate depending on the machine’s maximum stake and prize.
The phrase “net takings” is the part worth slowing down for. MGD is not a levy on turnover, on the money cycled through a machine. It is charged on the gross gaming yield: stakes in, minus winnings paid out. That amount is the machine’s gross margin, the practical expression of its house edge, and it is the pot from which rent, staff wages, machine rental, energy and business rates all have to be paid before anything reaches profit.
Five points sounds small. Look at where it lands.
A five-point rise on gross gaming yield is not a five per cent cost increase for an operator. It is five pence in every pound of machine gross profit, removed before any fixed cost is covered. On a venue running a thin net margin, that is a far larger proportional hit to the bottom line than the headline suggests.
This is the misreading worth correcting, and it costs people who make it a clear view of the sector. Reading “five points” as a modest adjustment assumes the tax scales with revenue and that a venue making less simply pays less. It does scale with yield, but the costs that yield has to carry do not shrink with it. A pub with four machines and an arcade with two hundred both face the same arithmetic: fewer pounds per machine against unchanged rent and staffing.
The standard reassurance, that a smaller-than-expected tax rise is absorbable, works for businesses with margin to absorb it into. Across much of UK retail gambling, that cushion is what has already been spent down over the past few years.
The relief was real, and so are the job warnings
Both reactions can be true at once because they are responses to different questions. Markets were pricing a tail risk that did not materialise. Venue operators are pricing a permanent reduction in the gross profit of the single most productive square metre in most of their estates.
What operators and trade bodies are saying
The Betting and Gaming Council has pointed to EY modelling indicating that a rise in Machine Games Duty to 40 per cent could cost up to 16,000 jobs and put 1,500 betting shops and 34 casinos at risk. Figures vary between reports, so treat the range rather than any single number as the signal. Entain has estimated an annualised additional cost of approximately £200m to its UK and Ireland online business from the new gambling taxes. The British Horseracing Authority has warned the higher duty could reduce racing revenues by as much as £57m a year, which matters because betting shop machine income feeds the levy and media rights payments that racing depends on.
These are projections and advocacy positions, produced by parties with an interest in the outcome, and they should be read as such. That does not make them empty. Trade bodies publishing modelling before a tax lands are also setting the benchmark against which they will judge it afterwards, which is a reasonable thing to watch.
Which parts of the workforce are most exposed
The exposure is concentrated, not spread evenly. Venues where machines carry a disproportionate share of gross profit feel the change first: seaside and high street amusement arcades, bingo halls, betting shops in lower-footfall locations, and smaller casino sites running on tight headcount.
Three practical responses are available to an operator facing a permanently thinner machine margin, and each has an employment consequence. Reducing machine counts cuts the duty base but also the revenue that justifies staffing hours. Cutting hours or shifts hits part-time and weekend roles hardest, which in arcades and bingo is a large share of the workforce. Closing marginal sites removes whole teams at once, along with the cleaning, maintenance and machine-servicing contractors attached to them. Warnings about casino job losses and arcade closures are describing those three levers, not a sudden collapse.
MGD does not arrive on its own
The reason a smaller tax rise still threatens jobs is that it joins a stack. Machine Gaming Duty sits alongside general betting duty, gaming duty on casino table play and remote gaming duty on online activity, and the land-based estate has absorbed several unrelated cost increases in parallel.
The statutory gambling levy, which funds research, prevention and treatment of gambling harm, is a cost licensees now carry as a proportion of their revenue. Employer wage and national insurance costs have risen across hospitality and leisure. Business rates and energy remain higher than pre-pandemic baselines for venues that cannot relocate demand online. And high street footfall in many of the towns where arcades and bingo halls operate has not recovered to earlier levels.
Any one of these is survivable. The gaming duty impact that operators describe is cumulative: a five-point reduction in machine gross margin applied to a cost base that has already been re-based upwards two or three times.
What a half-climbdown tells you about gambling tax policy
The gap between the feared increase and the delivered one is itself the story. A 40 per cent rise was in open circulation for weeks, modelled publicly by trade bodies, and attached to specific job and venue numbers. What arrived was a fraction of it. Whether that reflects lobbying, Treasury revenue modelling, or a deliberate anchoring of expectations, the pattern is now established on both sides.
The practical lesson for anyone following UK gambling regulation and taxation is that pre-Budget figures function as negotiating positions rather than forecasts, and that relief is becoming the sector’s default emotional response to a tax rise. That is a weak position to occupy. A duty that goes up by less than threatened still goes up, and the next cycle starts from the new, higher base, with the previous climbdown available as evidence that the industry can take it.
What is genuinely unsettled is whether the Treasury now treats machine duty as a reliable lever to be pulled again, or as a one-off correction. Nothing in the decision answers that.
What to watch before April 2027
The implementation date is the operative detail: the MGD rise does not bite until April 2027, which gives operators roughly a planning cycle to restructure estates and gives trade bodies time to keep lobbying for carve-outs or a phased introduction. Expect the legislative detail, including exactly how the five points apply across the duty bands, to be the focus of technical consultation responses.
Concrete signals to track in the meantime: machine count reductions reported in operator estate updates, any venue closure programmes announced ahead of the start date rather than after it, the next set of BGC and EY modelling revisions, and whether racing secures any compensating arrangement following the British Horseracing Authority’s £57m warning. If closures and headcount reductions appear in 2026 results rather than 2027, that tells you the duty was the trigger rather than the cause.